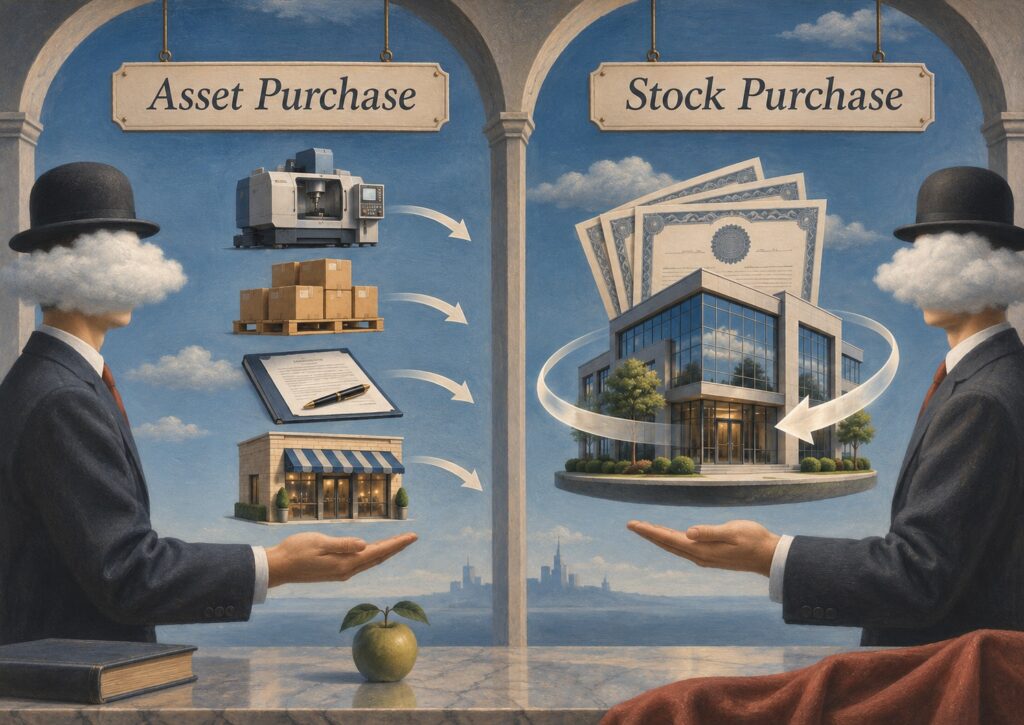
When buying a U.S. business, one of the first decisions is whether to purchase the company's assets or its ownership interests. That choice affects what you acquire, which liabilities remain with the business, what happens to its contracts and licenses, and how the transaction is taxed. It also affects the price a buyer is willing to pay and the amount a seller ultimately keeps.
In my earlier post on letters of intent, I explained that “generally speaking, sellers prefer stock deals and buyers prefer asset purchases.” In this post, I’ll explain why that is, and unpack some key considerations for each type of deal.
What an asset purchase actually is
In an asset purchase agreement, you're not buying the company itself. You're buying certain things the company owns, e.g.: equipment, inventory, sometimes receivables, and often the trade name. The seller's legal entity continues to exist after closing; it just holds onto whatever you didn't agree to buy, whatever employees you didn’t decide to hire (and they didn’t terminate), along with contracts and liabilities you didn’t choose to assume.
For buyers, this is fantastic. You can, in theory, cherry-pick the good stuff and leave the dregs behind. You also should be primed for favorable tax treatment as compared to purchasing stock (more on that below). In all, most small business M&A, including deals up to $10 million, are postured as asset purchases.
That’s not to say that larger companies never sell via asset purchase agreements. An asset sale is the default posture when a buyer acquires a discrete business line, or a division of a seller company (i.e., where that business line or division is not a distinct legal subsidiary). Alternatively, the seller in these deals can create a subsidiary and transfer in assets prior to closing, which brings its own set of considerations.
What a stock purchase actually is
In a stock purchase, you buy the seller's ownership interests; that is, the shares of a corporation or the membership interests of an LLC. The target company continues to exist exactly as it did pre-closing; it just has a new owner (you). Your new company arrives with all of its contracts, licenses, permits, tax ID numbers, and bank accounts intact. For a business whose value rests in hard-to-transfer assets (e.g. a liquor license, a government contract, or a lease with a “no assignments” clause), continuity is essential. But buyers must check for change-of-control restrictions, third-party consent requirements, and regulatory approvals. A stock purchase does not automatically eliminate those problems.
The trade-off in a stock sale is the inverse of an asset sale: you get everything, rather than some things, including certain things you cannot see. Every liability the purchased entity has—whether recorded, contingent, or completely unknown at closing—is now yours. The business’s history is now your history. Hopefully, you worked hard to identify potential snags in the diligence process, and dealt with them in the purchase agreement.
This complete transfer of ownership is why stock purchase agreements lean so heavily on reps and warranties, covenants, disclosure schedules, indemnification provisions, and escrows (including held-back funds). Such contract protections serve as stand-in for the structural shield an asset deal provides.
Finally, remember: a well-negotiated indemnity package with a long tail and a robust escrow can narrow the gap; but no indemnity is worth more than the strength of a seller's covenants, and most importantly, the money behind them.
The tax dimension
So much of M&A is tax driven. Under the U.S. tax code, buyers and sellers have structurally opposed preferences when assets or stock are sold. For this reason, it’s important to understand whether the seller entity is taxed as a corporation (subchapter C), a partnership (subchapter K), or a disregarded entity (no particular chapter), in order to make an informed offer. Make no assumptions here—a company’s corporate form and its tax status can be two different things.
In an asset purchase, a buyer typically gets a stepped-up basis in the acquired assets. In other words, you get the asset at fair market value, regardless of its depreciation history. You can then depreciate or amortize most of what you paid, generating tax deductions for years after closing. The seller's tax consequences depend heavily on how the business is taxed. A C corporation selling its assets can face two levels of tax: one when the corporation recognizes a gain, and another when the proceeds are distributed to shareholders. S corporations and LLCs taxed as partnerships generally avoid this double taxation, although an asset sale can still create significant tax costs for their owners.
In a stock purchase, there's no step-up in basis for the buyer, unfortunately. The company's assets keep their historic, depreciated basis, and you get no fresh deductions. Sellers tend to fare better in these deals, conversely, because the sale of stock or ownership interests is taxed at capital gains rates, and double taxation can be avoided.
Note: there are limited carve-outs—a Section 336(e) or 338(h)(10) election—that can produce asset-purchase tax treatment in a stock deal. However, these are only available in specific situations, such as acquisitions of S-corporation stock (and the parties must agree, complete certain pre-closing steps, and file consistently).
Finally, it’s worth noting that when the target is a C-corporation, buyers demanding an asset sale often must pay a higher purchase price (a “gross up”) to compensate the seller for paying tax at both the company and shareholder levels. When the target is an S-corporation or an LLC taxed as a partnership, bridging the gap is cheaper and easier.
Non-tax considerations
Tax is not the only determining factor as to whether stock or assets are sold. Other factors may drive the structure, and the parties should address the economics accordingly.
First, an asset purchase often isn’t feasible with large target businesses (think, $50M+ in annual sales). If the target is pulling revenues at this level with a complex corporate structure, hundreds of employees, or a cross-border footprint, then itemizing and transferring each individual asset becomes logistically impractical.
Second, and to that point, asset deals are administratively heavier. Every asset you buy must be transferred: bills of sale, assignments of contracts, trademark assignments, etc. If the business depends on a key contract, as so many do, you'll likely need the counterparty's written consent to assign it (small business landlords, in particular, can be frustrating). And yes, third parties often have outsized leverage here, and may extract a toll for their signature.
Third, buying assets does not always mean you will land free and clear. Courts can impose successor liability in asset deals on various theories. Typical examples include where the buyer is deemed a "mere continuation" of the seller, or when the transaction is structured to short creditors. If you plan to keep the same employees, same location, same phone number, and same name, a plaintiff's lawyer may argue the business never really changed hands. Depending on the applicable law, a buyer can face successor liability if it assumes certain obligations, the transaction amounts to a de facto merger or continuation of the seller, or the sale is designed to evade creditors. Employment, tax, and other statutory obligations can present additional risks. Buyers should investigate these issues even when the purchase agreement says they are acquiring assets free of liabilities.
So, which form of acquisition should you choose?
There's no universal answer, but here is the default: in small and mid-sized deals, buyers generally prefer asset purchases, sellers generally prefer stock sales, and the final structure is a negotiated outcome—often priced in accordance with the agreement’s final form. If the target's value is concentrated in transferable assets and the risk profile contains unknowns, the asset deal's liability shield and tax step-up usually win. If the business runs on licenses, contracts, or permits that can't realistically be reassigned, the stock deal's continuity may require accepting the broader liability exposure—provided the reps, indemnities, and escrow are tailored accordingly.
Finally, one practical note before you circulate or sign a letter of intent, even if non-binding: the structure outlined in the LOI sets a negotiating baseline, and it sets expectations. A responsible buyer will decide whether an asset or stock purchase deal is on offer before the LOI goes out. Happy shopping.
For earlier posts in this series, check out the following:
- Buying a Business in the U.S., Part 1: How to Find Them
- Buying a Business in the U.S., Part 2: How to Price Them
- Buying a Business in the U.S., Part 3: Nondisclosure Agreements
- Buying a Business in the U.S., Part 4: Letters of Intent (LOIs)
- Buying a Business in the U.S., Part 5: Due Diligence
- Buying a Business in the U.S., Part 6: Purchase Price Adjustments